Opening a corporate bank account is an important step after setting up a company in the UAE. A business bank account allows companies to receive client payments, pay suppliers, manage expenses and build a proper financial structure.
However, obtaining a trade licence does not automatically guarantee immediate approval of a UAE corporate bank account.
Some applications move smoothly, while others take longer because the bank requires additional information, documents or clarification about the company and its business activities.
If you are planning to open a corporate bank account in Dubai or anywhere in the UAE, understanding what banks typically review can help you prepare a stronger application and reduce avoidable delays.
Why Does Corporate Bank Account Opening Take Time in the UAE?
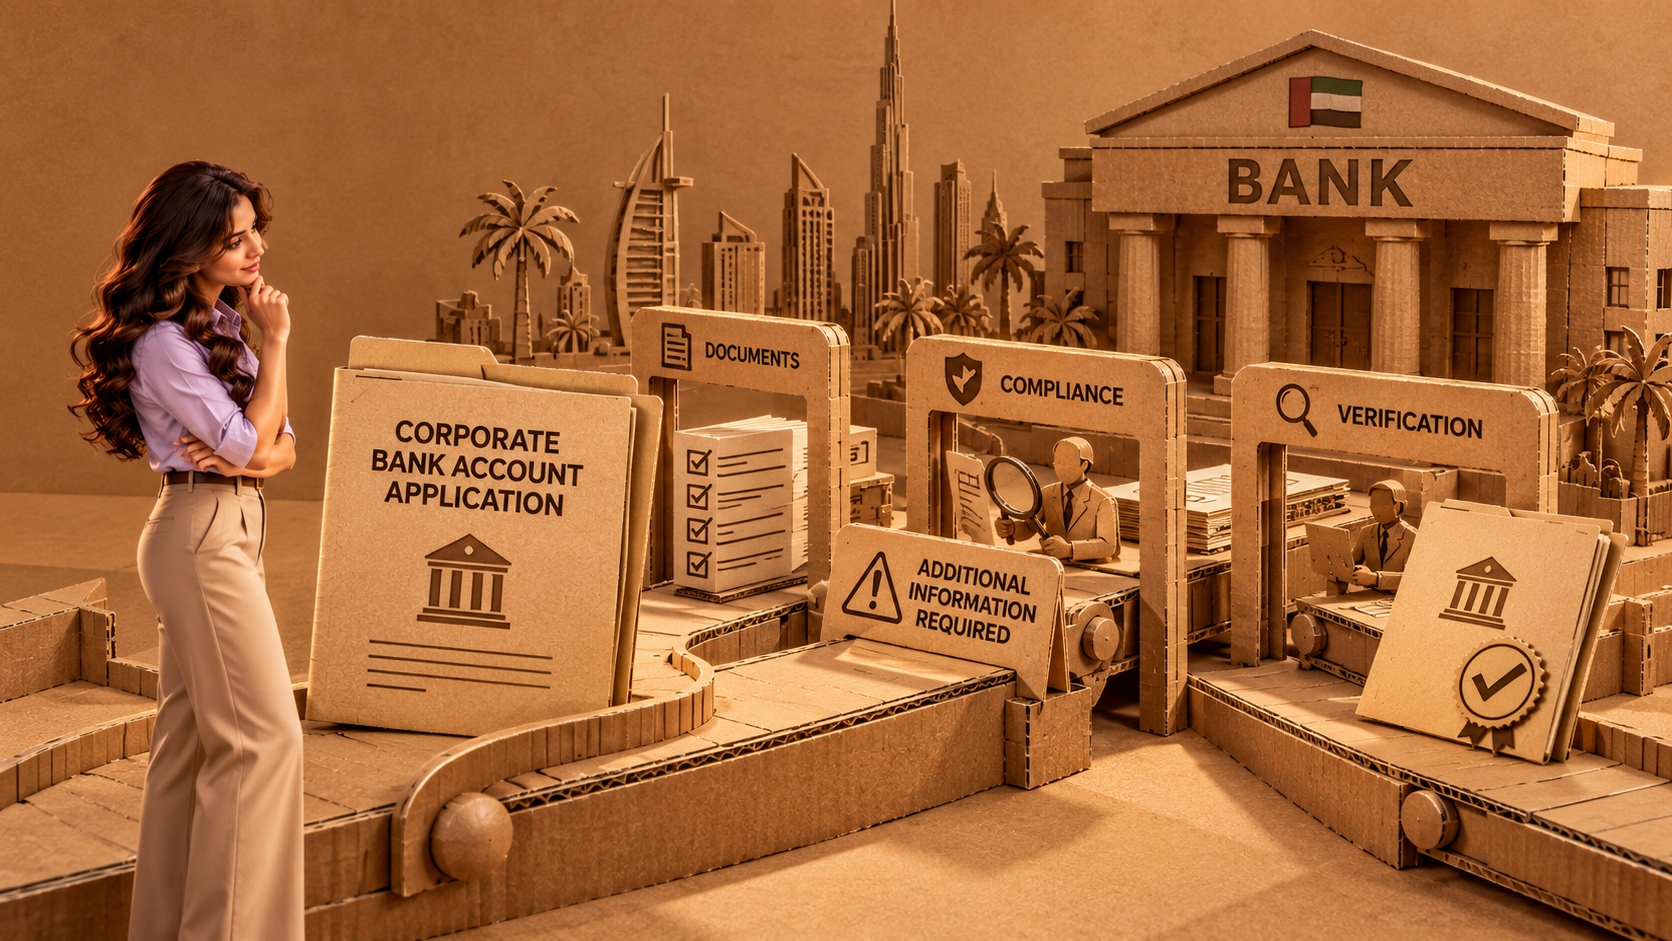
UAE banks conduct compliance and due-diligence checks before approving a corporate account.
The bank needs to understand who owns the company, what the business does, where its money will come from, who its customers and suppliers are, and how the account is expected to be used.
The exact requirements and processing time can differ between banks and applicants.
A delay does not necessarily mean that an application will be rejected. In many cases, the bank simply needs more information before completing its review.
Here are some common reasons a UAE business bank account application may take longer.
1. Incomplete or Inconsistent Company Documents
One of the most avoidable causes of delay is missing or inconsistent documentation.
Depending on the company and bank, you may be asked to provide documents such as:
- UAE trade licence
- Certificate of incorporation or registration documents
- Memorandum or Articles of Association
- Shareholder and authorised signatory identification
- Passport and UAE residency documents where applicable
- Proof of address
- Company ownership information
- Business plan or company profile
- Supporting commercial documents
If information differs between documents, the bank may request clarification.
Before submitting a corporate bank account application in the UAE, make sure company names, shareholder details, business activities and other key information are consistent.
2. Your Business Activity Is Not Clearly Explained
A trade licence tells the bank what activities the company is licensed to conduct, but it may not fully explain how the business actually operates.
Banks may want to understand:
What does your company sell? Who are your customers? Where are they located? Who are your suppliers? How will the company generate revenue?
A vague description such as “consultancy” or “general trading” may not provide enough commercial context by itself.
A clear company profile and business model can help the bank understand the purpose of the account and the expected transactions.
3. Lack of Proof of Genuine Business Activity
A newly formed company may not have a long trading history, but banks can still request evidence that demonstrates the intended commercial activity.
Depending on your business, useful supporting documents could include contracts, invoices, quotations, supplier agreements, purchase orders, client correspondence or a professional company website.
The specific evidence required will depend on the bank and the nature of the business.
For a new company, being able to clearly explain how the UAE business will operate and generate revenue is particularly important.
4. Source of Funds Needs Further Clarification
Banks need to understand where money entering the account is expected to come from.
This can include the source of the initial capital as well as future business revenue.
If the bank cannot clearly establish the source of funds or source of wealth, it may request additional supporting documents.
Providing clear and accurate information from the beginning can help reduce unnecessary back-and-forth during the compliance review.
5. Complex Shareholding or Ownership Structure
A company with a straightforward ownership structure may be easier for a bank to assess than one involving several shareholders, holding companies or corporate shareholders across multiple jurisdictions.
Banks generally need to identify and verify the company's ultimate beneficial owners (UBOs).
Where the ownership chain is complex, additional corporate documents may be necessary to establish who ultimately owns or controls the company.
This can extend the UAE corporate bank account opening process.
6. High-Risk or Regulated Business Activities
Not every industry carries the same compliance profile.
Certain sectors, business models, transaction patterns or geographic relationships can require enhanced due diligence.
Banks may therefore ask for additional information about customers, suppliers, transaction flows, licences or regulatory approvals.
This doesn't automatically mean that the company cannot obtain a bank account. It means the bank may conduct a more detailed review before making its decision.
7. Expected Transactions Are Not Clearly Defined
Banks may ask about your anticipated banking activity, including:
- Expected monthly turnover
- Average transaction value
- Main currencies
- Countries you expect to send or receive money from
- Key customers and suppliers
- Types of incoming and outgoing payments
If the expected transactions do not appear consistent with the company's stated business activity, the bank may ask further questions.
When applying for a business bank account in Dubai or the UAE, provide realistic estimates rather than numbers chosen simply to make the company appear larger.
8. Weak UAE Business Presence
Banks may consider the company's overall commercial substance and connection to the UAE as part of their assessment.
Depending on the circumstances, they may review factors such as the company's registered address, office arrangements, residency status of relevant parties, local operations and commercial relationships.
Requirements vary significantly between banks and business models, so this should be assessed before choosing where to apply.
9. Choosing a Bank That Does Not Suit Your Business Profile
A common mistake is assuming that every UAE bank evaluates every business in exactly the same way.
They don't.
Different banks can have different onboarding criteria, compliance requirements and preferences regarding business activities, ownership structures and transaction profiles.
The bank that works well for one company may not necessarily be the most suitable option for another.
This is why UAE corporate banking assistance should start with understanding the business profile rather than simply submitting applications everywhere.
How Can You Reduce Delays When Opening a UAE Corporate Bank Account?
Preparation matters.
Before approaching a bank, make sure your company information tells one consistent story. Your licence activity, company profile, ownership structure, expected transactions, customers, suppliers and source of funds should make commercial sense together.
You should also have the supporting documentation ready to substantiate the information provided in the application.
Avoid submitting inaccurate information simply because you think it will improve your chances. Banks conduct their own due diligence, and inconsistencies can create more questions rather than fewer.
Can a Free Zone Company Open a Corporate Bank Account in the UAE?
A UAE free zone company can apply for a corporate bank account, subject to the chosen bank's onboarding and compliance requirements.
Being incorporated in a free zone does not by itself guarantee approval or rejection.
Banks will assess the overall profile of the company, including its activities, ownership, expected transactions and supporting documentation.
Similarly, a Dubai mainland company must still go through the bank's onboarding and compliance process.
Therefore, the question shouldn't simply be “mainland or free zone?” It should be whether the company's complete profile meets the chosen bank's requirements.
How Long Does Corporate Bank Account Opening Take in the UAE?
There is no reliable universal timeline.
The process can depend on the bank, business activity, ownership structure, documentation, compliance review and whether additional information is requested.
Be cautious of anyone promising guaranteed bank account approval within a fixed number of days. The final decision belongs to the bank.
A better objective is to prepare the application properly so that avoidable issues do not slow down the review.
How AD Firms Can Help With UAE Corporate Banking
At AD Firms Business Services, we help entrepreneurs and companies prepare for the UAE corporate banking process by reviewing their business profile and supporting documentation and assisting them in understanding suitable banking options.
Our support can include guidance around company documentation, business activity information, ownership details and other information that may be required during corporate bank account onboarding.
Whether you're completing a new company formation in Dubai, establishing a UAE free zone company, or already have an existing UAE business, preparing the banking side early can prevent unnecessary complications after receiving your trade licence.
Bank account approval remains subject to the individual bank's compliance checks, policies and final decision.
Final Thoughts
Delays in UAE corporate bank account opening are often caused not by one single problem, but by gaps between the company's documents, business model, ownership information and expected financial activity.
The stronger and more consistent your application is, the easier it is for the bank to understand your business.
If you're planning to set up a company and open a corporate bank account in the UAE, prepare the banking requirements alongside your company formation rather than treating banking as an afterthought.
AD Firms Business Services can assist you with UAE company formation and corporate banking support so you can approach the process with the right documentation and business information from the beginning.